The Kelly Criterion, and Why Nobody Runs Full Kelly
Key takeaway
The Kelly criterion says bet 10% per trade on a 55/45 edge — the growth-optimal fraction. Simulated over 200 trades, that same fraction produces a 50% peak-to-trough drawdown in 93% of runs, and ends below half the starting capital once in ten. Half Kelly keeps three-quarters of the growth and a fraction of the pain.
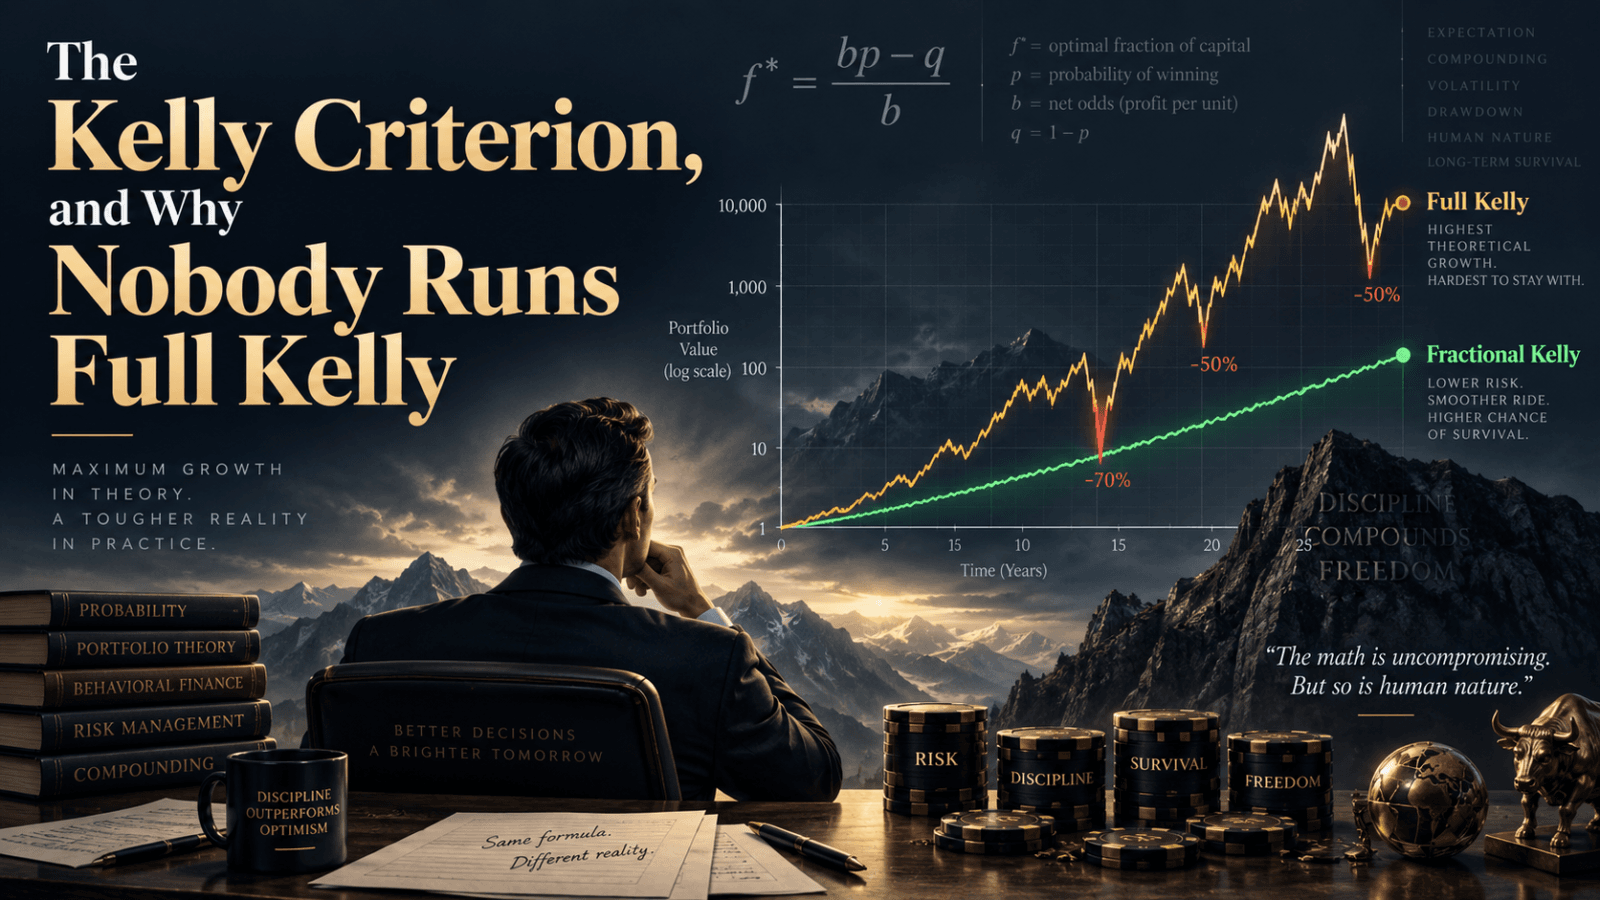
The Kelly criterion answers a question every trader avoids: given an edge, exactly how much of the account should ride on the next bet. For a genuinely good edge — winning 55% of the time at even money — the formula says risk 10% of the account per trade. Almost nobody who knows the formula actually does that, and the reason is not caution for its own sake. It is that at the growth-maximising fraction, a peak-to-trough fall of half the account stops being a tail risk and becomes the normal case: in simulation it happens in 93% of runs. Growth-optimal and survivable are two different specifications.
This article derives the number, simulates what actually happens at that number and at half of it, and explains why anyone who uses the formula in practice tends to bet a fraction of what it recommends.
What the formula says
For a bet with two outcomes and even-money payoff — win an amount equal to what you risk, or lose what you risked — the Kelly fraction simplifies to:
f* = p − q
where p is the probability of winning and q (= 1 − p) is the probability of losing. A trader who wins 55% of the time with a 1:1 reward-to-risk ratio has f* = 0.55 − 0.45 = 10%. That is the fraction of current equity to risk on the next trade — not the fraction to buy with, the fraction to lose if the stop is hit.
The general formula for an uneven payoff is f* = p − q/b, where b is the reward-to-risk ratio. This article keeps b = 1 throughout, the same 55%-win-rate scenario used in our position sizing and risk of ruin piece, so the two articles can be read side by side.
What Kelly maximises, and what it does not
Kelly maximises the expected logarithm of wealth — the compounding rate a typical path settles into — and not the expected value of the account. The distinction sounds academic until the numbers are on the table, at which point it turns out to be the whole subject.
| Risked per trade | Expected log-growth per trade | Typical (median) result after 200 trades |
|---|---|---|
| 2% | +0.180% | 1.43× |
| 5% (half Kelly) | +0.375% | 2.12× |
| 10% (full Kelly) | +0.501% | 2.72× — the maximum |
| 15% | +0.374% | 2.11× |
| ~20% (≈ 2× Kelly) | −0.014% | 0.97× — the edge is gone |
| 25% | −0.673% | 0.26× — a typical loser, despite winning 55% of trades |
Read the last row carefully, because it is easy to misread. At 25% risk per trade the typical outcome is losing about three-quarters of the account, even though the strategy wins more often than it loses. But the average outcome across all possible runs at that same 25% is 139.6× — the arithmetic expectation is not just positive, it is enormous.
Both numbers are correct, and the gap between them is the point. The average is dragged upward by a vanishingly small set of paths that win almost every trade, outcomes so rare that no individual trader should plan around them. The median describes what happens to nearly everyone. The practical consequence: maximising the expected value of the account and maximising the growth rate you will actually experience are different objectives, and Kelly deliberately optimises the second one.
The number that should worry you: about 20%
Kelly’s fraction is not the point past which betting becomes merely riskier. It is the peak of a curve: expected log-growth rises up to f*, falls away on the other side, and crosses zero at roughly twice the Kelly fraction — for this edge, at 19.87%. Past that point a strategy that is right more often than it is wrong has, typically, no growth at all, and then negative growth. Nothing about the edge changed; only the bet size did.
The round-number version worth remembering is that about double Kelly consumes the entire edge. Betting exactly 20% here gives −0.014% per trade, which compounds to 0.97× over 200 trades: not quite the zero point, close enough to it that the distinction stops mattering.
What full Kelly actually feels like
Growth-optimal says nothing about what a single 200-trade run looks like, and the spread around that median at full Kelly is enormous. We simulated 400,000 independent runs of 200 trades at each risk level (55% win probability, 1:1 payoff, fixed-fractional sizing on current equity), and recorded the drawdowns and the range of final outcomes.
| Risked per trade | Odds of a 50%+ peak-to-trough drawdown | Odds of ever falling below half the starting capital | Median | 10th percentile | 90th percentile |
|---|---|---|---|---|---|
| 2% | 0.1% | 0.0% | 1.43× | 1.00× | 2.05× |
| 5% (half Kelly) | 27.3% | 7.9% | 2.12× | 0.86× | 5.21× |
| 10% (full Kelly) | 93.0% | 38.2% | 2.72× | 0.45× | 16.57× |
| 15% | 99.9% | 62.6% | 2.11× | 0.14× | 32.06× |
| 20% | 100.0% | 78.5% | 0.97× | 0.03× | 37.40× |
The two drawdown columns measure different things and both are worth having. The first is the real one — the fall from a running high-water mark, which is what an investor actually experiences and what a track record reports. The second is the cruder question of whether the account ever halved relative to where it began. An account that runs from 1× to 3× and back to 1.4× never triggers the second column and has still lost more than half its value from the peak.
By the honest measure, full Kelly produces a 50%+ drawdown in 93% of runs. That is not a tail scenario to be acknowledged and dismissed; it is the default experience of betting the growth-optimal fraction. One run in ten also ends below 0.45× — a 55% loss after 200 trades, with the edge intact and working exactly as specified the entire time.
Half Kelly lowers the median outcome from 2.72× to 2.12× — it retains about three-quarters of full Kelly’s log-growth rate — and in exchange cuts the odds of a 50% drawdown from 93% to 27%, and lifts the 10th-percentile outcome from 0.45× to 0.86×: still a loss of 14%, but a recoverable one rather than a crippling one. The practical consequence: the fraction that maximises growth on paper is not a fraction most people can hold through, and a rule that gets abandoned mid-drawdown was never really the rule being followed.
The assumption that breaks first: the edge itself
Everything above takes p as known. In practice it is estimated from a finite track record, and the formula has no margin built in for being wrong about it. The consequences of a small estimation error are worse than intuition suggests.
Suppose the true win rate is 52.5% and you believe it is 55%. Your estimated Kelly fraction is 10%; your true one is 5%. You are betting exactly double your real Kelly — and the zero-growth point for your real edge sits at 9.98%. Betting 10% therefore delivers a log-growth rate of roughly zero: over 200 trades, 0.998×. An overestimate of two and a half percentage points in the win rate is enough to convert a genuine edge into no growth at all, while every individual trade still carries positive expected value.
Two further assumptions deserve naming, because the simplified model used here leans on both:
- Independent, identically distributed trades. The version of Kelly in this article assumes each outcome is unrelated to the others and drawn from the same distribution. Strategies that cluster trades — several correlated positions open at once, or losing trades that bunch up in the same market regime — behave like fewer, larger bets than that model assumes. The criterion itself can be generalised well beyond this case; the arithmetic here cannot.
- A clean two-outcome payoff. Real trade outcomes have fat tails and gaps, and a stop-loss does not always fill at the stop. The 1:1 binary version is the textbook case that makes the mechanism legible, not a claim that trading looks like it.
All three push in the same direction: toward a fraction below whatever the formula returns for your best estimate of the edge.
The practical rule
Compute f* honestly from a measured win rate and payoff, not a hoped-for one. Then bet a fraction of it — half is the fraction most commonly discussed in the practitioner literature, a third or a quarter where the inputs are less trustworthy — and treat the reduction not as leaving money on the table but as the price of a drawdown you can actually sit through. Fixed-fractional sizing and the volatility and correlation adjustments covered in our position sizing article are how that reduced number gets implemented trade by trade; Kelly is where the number comes from in the first place.
Frequently asked questions
What is the Kelly criterion?
A formula that gives the fraction of capital to risk on a bet with a known edge in order to maximise the long-run growth rate of wealth — specifically, the expected logarithm of wealth. For an even-money bet it is simply your win probability minus your loss probability.
How do you calculate the Kelly fraction for trading?
For a 1:1 reward-to-risk trade, f* = win rate − loss rate. A 55% win rate gives f* = 10%. For uneven payoffs the full formula is f* = p − q/b, where b is the reward-to-risk ratio.
Why doesn’t anyone bet full Kelly?
Because the ride is close to unbearable. In simulation, full Kelly on a 55/45 edge produces a 50%+ peak-to-trough drawdown in 93% of runs, and one run in ten ends 55% down after 200 trades — with the edge real and unchanged throughout. Growth-optimal is not the same as tolerable.
What is half Kelly and why is it common practice?
Betting half the Kelly fraction. In this scenario it keeps about 75% of full Kelly’s log-growth rate while cutting the odds of a 50% drawdown from 93% to 27%, and improving the 10th-percentile outcome from 0.45× to 0.86×. Thorp discusses the case for fractional Kelly directly, on essentially these grounds.
What happens if you bet more than double the Kelly fraction?
Typical growth turns negative. For the 55/45 edge used here the zero-growth point is 19.87% risked per trade, so a strategy that wins more often than it loses can still be a typical loser at that size, purely from position sizing.
What happens if you overestimate your win rate?
You bet above your true Kelly fraction without knowing it, and the margin for error is thin. Believing a 52.5% edge is 55% leads you to bet 10% when your real Kelly is 5% — which is almost exactly the point at which your real edge produces no growth at all. This is the strongest practical argument for sizing to a fraction of the computed number.
This article is general information, not personalised investment advice. It does not take into account the financial situation, objectives or risk tolerance of any individual reader, and the same text is distributed to all readers. The 55% win rate, 1:1 payoff scenario is an illustrative example, not a claim about any specific trading strategy’s actual edge; simulated results describe that scenario only and are not a forecast. Trading and investing involve the risk of loss, including loss of principal, and past performance does not indicate future results.
Sources
- Kelly, J.L. Jr. (1956). A New Interpretation of Information Rate. Bell System Technical Journal, 35(4), 917–926. The original derivation of the growth-optimal betting fraction.
- Thorp, E.O. (2006). The Kelly Criterion in Blackjack, Sports Betting, and the Stock Market. Chapter 9 in Handbook of Asset and Liability Management, Volume 1, ed. S.A. Zenios and W. Ziemba, Elsevier, DOI 10.1016/S1872-0978(06)01009-X. Section 7.3, “The case for ‘fractional Kelly'”, is the source for the fractional-Kelly discussion above. The paper was first presented in 1997 and published in Finding the Edge (2000), with corrections added in 2005.
- The growth-rate table and the zero-growth point are our own calculations: expected log-growth g(f) = p·ln(1+f) + q·ln(1−f), solved numerically for its positive root (19.8668% for p = 0.55). The arithmetic expectation quoted for 25% risk is (1 + f(p−q))200 = 139.6×.
- The drawdown and dispersion figures are our own simulation: 400,000 independent 200-trade paths per risk level, 55% win probability, 1:1 payoff, fixed-fractional sizing on current equity. Drawdown is measured peak-to-trough against a running high-water mark; the second column reports the separate, weaker condition of the equity ever falling below half its starting value.
Related reading
- Position sizing and the risk of ruin — fixed-fractional sizing, correlation and volatility adjustment: how the Kelly number survives contact with a real portfolio.
- Portfolio hedging strategies: what each one costs — the same question of paying for protection versus sizing your way out of the risk, applied to instruments rather than trade sizing.
- How to manage investment risk — where position sizing sits in the full hierarchy of risk decisions.
- Which algorithmic trading strategies are actually profitable? — evidence and backtests for the kind of measured edge this article assumes as an input.
Advertisement