How to Manage Investment Risk: The Hierarchy That Decides Your Outcome
Key takeaway
Risk management is a hierarchy, not a checklist. Position sizing decides most of the outcome, then asset allocation, then never becoming a forced seller. Diversification and rebalancing follow, and explicit hedges come last. The ordering matters more than the list, because a 50% loss requires a 100% gain just to break even.
Most advice on managing investment risk arrives as a list of ten tips presented as equals: diversify, review regularly, stay informed, control your emotions. They are not equals. One of those decisions determines most of your outcome and the rest are refinements, and almost every list gets the order wrong.
This guide separates the four different things people call “risk”, ranks the decisions that actually control them by how much each one moves the result, and covers the arithmetic that explains why avoiding large losses matters disproportionately more than capturing large gains.
The four risks people conflate
“Risk” is used for at least four distinct problems, and the defence against each is different. Treating them as one thing is why generic advice fails.
| Risk | What it means | What actually defends against it |
|---|---|---|
| Volatility | The value fluctuates. Uncomfortable, but recoverable by waiting if the asset is sound | Time horizon, and holding nothing you would be forced to sell early |
| Permanent loss of capital | The asset does not come back — the company fails, the token dies, the thesis was wrong | Position sizing and diversification. Nothing else works once it has happened |
| Liquidity risk | You cannot exit at a fair price when you need to | Owning liquid instruments and holding a cash buffer so you are never a forced seller |
| Sequence risk | The order of returns matters when you are adding or withdrawing money. The same average return can leave you solvent or not | Asset allocation matched to when you need the money, not to your appetite for excitement |
The practical consequence: volatility is the risk most investors try to manage and the one that matters least if the horizon is genuinely long. Permanent loss is the one that ends portfolios, and it is controlled almost entirely before you buy anything — by deciding how much.
The hierarchy: what actually controls risk
Ranked by how much each decision moves the outcome, from most to least.
| Rank | Decision | Why it sits here |
|---|---|---|
| 1 | How much of your capital any single idea represents | Determines whether being wrong is a setback or an ending. Dominates every other choice |
| 2 | Your allocation across asset classes | Explains the large majority of portfolio return variation over time — far more than security selection |
| 3 | Whether you can avoid becoming a forced seller | An emergency fund is a risk management tool. Selling into a crash to pay a bill converts volatility into permanent loss |
| 4 | Genuine diversification, not the appearance of it | Twelve holdings in the same sector is one position with extra paperwork |
| 5 | Rebalancing on a rule rather than a feeling | Mechanically trims what has run and adds to what has lagged, without requiring a forecast |
| 6 | Explicit hedges — options, inverse funds, currency overlays | Useful, costly, and only worth considering once the five above are settled |
The ordering is the point. An investor with correct position sizing and a crude portfolio will outlast one with elegant hedges and a concentrated bet.
Position sizing: the decision that dominates
Every other technique on the list assumes you are still in the game. Position sizing is what keeps you there.
The question is not “is this a good investment?” but “if this goes to zero, what happens to me?” A conviction that turns out to be wrong at 3% of a portfolio is a lesson; the same conviction at 40% is a different life. Note that the quality of the analysis does not enter into this — you can be right about the asset and still be destroyed by the size, because being right eventually is not the same as being solvent throughout.
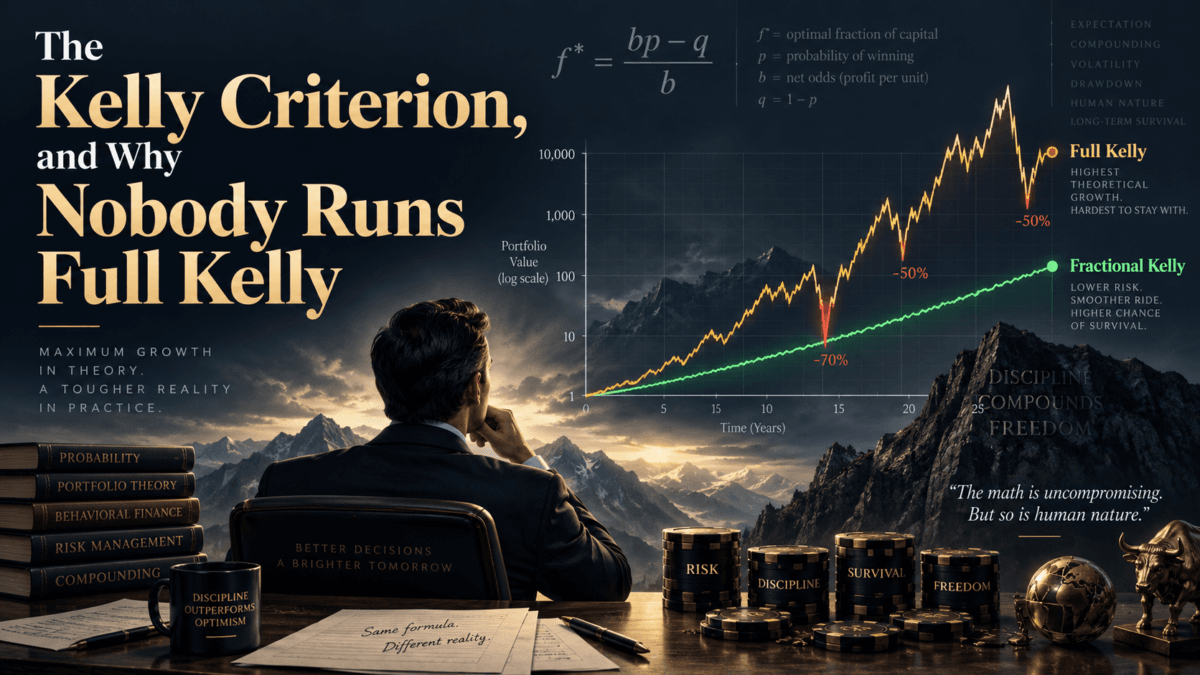
The full arithmetic, including how consecutive losses compound faster than intuition suggests, is in our guide to position sizing and the risk of ruin.
The drawdown arithmetic nobody teaches
Losses and gains are not symmetrical, and the asymmetry grows brutally as losses deepen. To recover from a fall you need a percentage gain larger than the percentage you lost, because you are earning it on a smaller base.
| Loss | Gain required to break even |
|---|---|
| −10% | +11.1% |
| −20% | +25% |
| −30% | +42.9% |
| −40% | +66.7% |
| −50% | +100% |
| −60% | +150% |
| −70% | +233% |
| −80% | +400% |
| −90% | +900% |
The practical consequence: this table is the entire argument for risk management in one place. Below about −50% the recovery required stops being a matter of patience and starts requiring a return most assets do not produce. Everything in this guide exists to keep a portfolio out of the bottom rows.
What diversification does and does not do
Diversification is the most repeated advice in investing and the most frequently misapplied.
What it does: removes the risk specific to one company or one asset. If a holding fails for reasons unique to it, a diversified portfolio absorbs the loss without permanent damage. This is the risk that position sizing and diversification together eliminate almost completely, and it is free — there is no return penalty for not concentrating.
What it does not do: protect against the market falling as a whole. In serious dislocations, correlations between assets that normally move independently converge toward one, and the diversification you thought you had disappears at the moment you need it. This is not a flaw in the technique; it is the definition of a systemic event.
What it is not: owning many things. Twenty technology stocks is a concentrated bet on one sector. Three funds tracking overlapping indices is one fund with three sets of fees. Genuine diversification requires holdings that respond to different drivers — and the honest test is to ask what single piece of news would damage everything you own at once. Our guide to resilient sectors in times of volatility covers which exposures have historically behaved differently under stress.
The tools most people reach for first
Stop-loss orders
A stop-loss converts an open-ended loss into a defined one, which is genuinely valuable for a trading position with a thesis that can be invalidated at a price. For a long-term investment it is a blunter instrument than it appears: it guarantees you sell during volatility, which is precisely when a sound asset is most likely to recover. Stops are a trading tool applied to an investing problem more often than they should be.
Hedging
Explicit hedges — put options, inverse funds, currency overlays — reduce specific exposures at a specific cost. They are real tools and they work; they are also a continuous drag on returns, which is what you are paying for the protection. They belong last on the list because most portfolios that need hedging actually need smaller positions. The mechanics are covered in portfolio hedging strategies.
Rebalancing
Setting a target allocation and returning to it on a schedule or a threshold is the most underrated item here. It requires no forecast, it enforces selling strength and buying weakness automatically, and it prevents a winning position from silently growing into a concentration risk you never chose.
The part that is not technical
Every method above fails at the same point: when the investor abandons it. Plans are written in calm markets and tested in falling ones, and the most common failure is not a bad framework but a good framework overridden at the worst moment.
Two things help more than willpower. The first is writing the rules down before you need them, including what would make you sell — a decision made in advance is easier to honour than one made during a drawdown. The second is sizing positions so that no single outcome produces the emotional pressure that breaks the plan. If a position keeps you awake, that is risk information, not weakness.
Our guides to behavioural finance and identifying your investor profile cover the mechanisms behind this in more detail.
Frequently asked questions
How do you manage investment risk?
In order of impact: size positions so no single failure is fatal, set an asset allocation matched to when you need the money, keep enough cash that you are never a forced seller, diversify across genuinely different drivers rather than many similar holdings, rebalance on a rule, and only then consider explicit hedges. The ordering matters more than the list.
What is the most important risk management strategy?
Position sizing. Every other technique assumes you still have capital to deploy, and position sizing is what determines whether a wrong decision is recoverable. It is also the only one that works against permanent loss, which is the risk that actually ends portfolios.
Does diversification eliminate risk?
No. It removes risk specific to individual holdings almost entirely, at no cost in expected return. It does not protect against market-wide declines, because in serious dislocations correlations between normally independent assets converge and the diversification benefit shrinks exactly when it is needed.
Are stop-loss orders a good risk management tool?
For trading positions with a price level that invalidates the thesis, yes. For long-term investments they are weaker than they look, because they guarantee selling during volatility — which is when a fundamentally sound asset is most likely to be temporarily mispriced.
How much should I invest in a single position?
There is no universal figure, and it depends on your total capital, horizon and what else you hold. The useful framing is not a percentage but a question: if this position went to zero, would the portfolio recover, and would you still follow your plan? If the answer to either is no, the position is too large.
Why do I need a bigger gain than my loss to break even?
Because the gain is earned on a reduced base. A 50% loss leaves half your capital, which must then double — a 100% gain — to return to the starting point. The asymmetry worsens sharply beyond that: a 90% loss requires a 900% gain.
The decision that keeps all of this in place over time is maintenance. How often you should rebalance your portfolio covers what drift costs in drawdown and how to correct it without realising a gain.
Related reading
- Why bond yields rise when central banks cut rates — duration, the risk most bond holders never measure.
- Position sizing and the risk of ruin — the arithmetic behind the first item in the hierarchy.
- Portfolio hedging strategies: what each one costs — the specific instruments, once the fundamentals are settled.
- The Sharpe ratio — measuring return against risk, and where the measure misleads.
- Portfolio construction in 2026 — the allocation decision that ranks second in the hierarchy.
- Crisis-proof investments — which exposures have historically behaved differently under stress.
- Behavioural finance — why sound plans get abandoned at the worst moment.
This article is general information, not personalised investment advice. It does not take into account the financial situation, objectives or risk tolerance of any individual reader, and the same text is distributed to all readers. Capital is at risk and past performance does not indicate future results.