Technical vs Fundamental Analysis: What 145 Years of Market Data Say About Each
Key takeaway
On US data since 1881, valuation (CAPE) explained a quarter of the next decade's return and almost nothing about the next month; the price trend explained little about returns but flagged the riskiest months. Turned into simple rules from 1927 to 2026, neither beat holding the market, and both factor premiums shrank after publication.
Fundamental analysis estimates what an asset is worth from the business behind it. Technical analysis reads price and volume to judge what other investors are doing. Asking which is better is usually answered with opinions. It can be answered with arithmetic: take the plainest signal of each kind, run both on the same 145 years of US stock market data, and measure what each one actually knew.
We did that with Robert Shiller’s cyclically adjusted P/E (CAPE) as the fundamental signal and the market’s position against its 10-month moving average as the technical one, with data to October 2026:
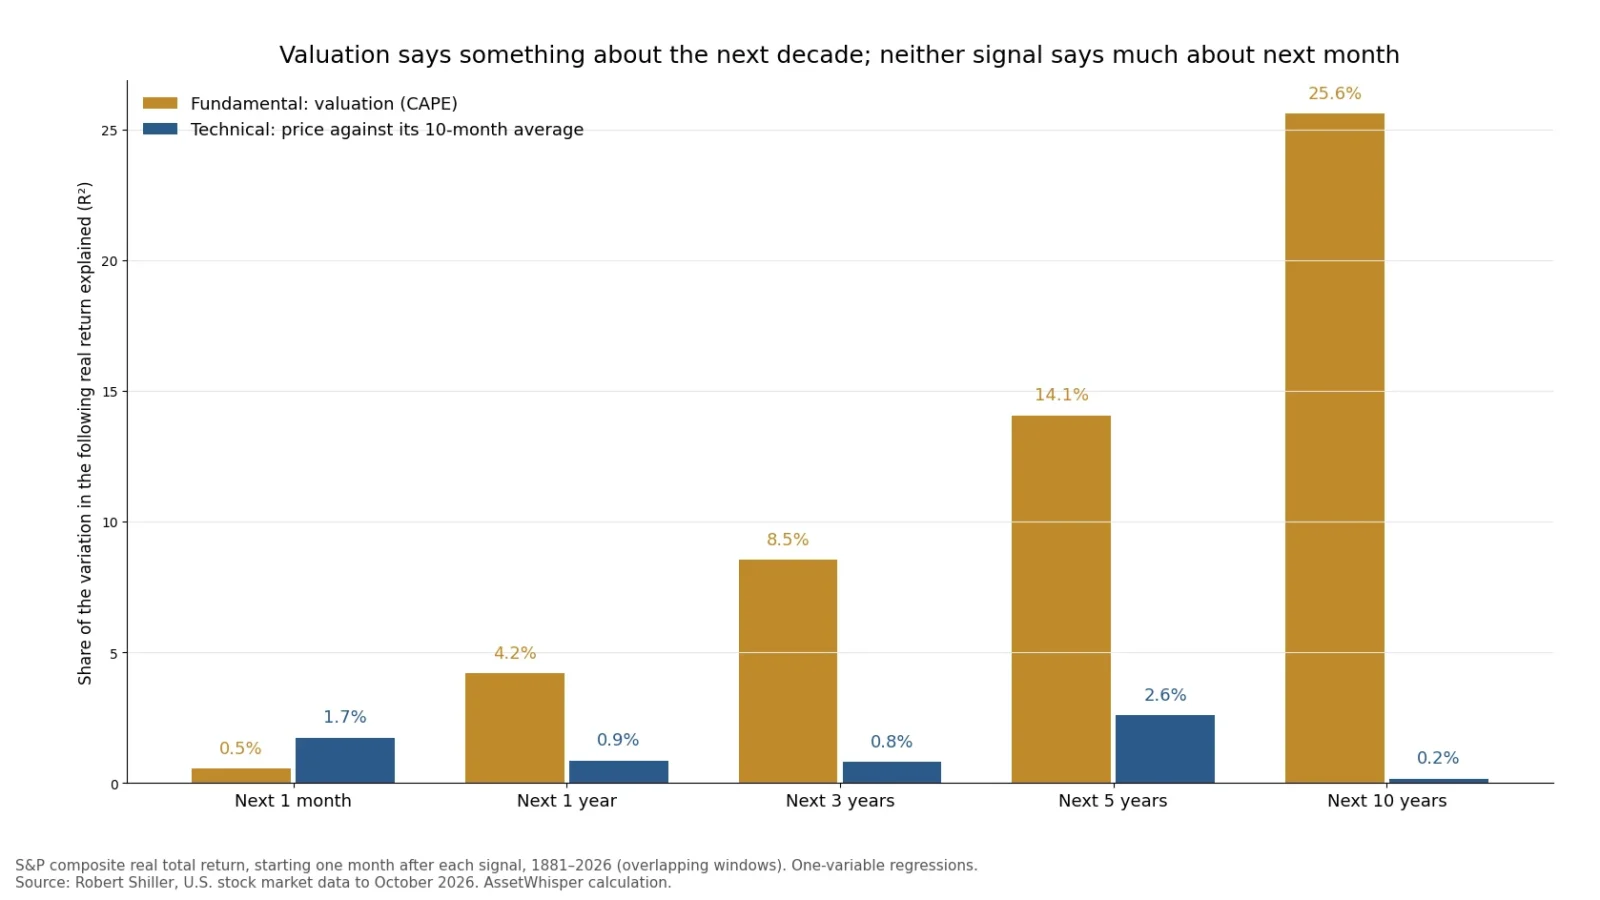
- They know different things. Valuation explained 25.6% of the variation in the following ten years’ real return and 0.5% of the following month’s. The price trend explained less than 3% at every horizon.
- The technical signal is about risk, not return. After a month-end below the 10-month average, the next month was almost twice as volatile (26.0% a year against 14.6%), and 19 of the 31 months worse than −10% since 1927 started there.
- Turned into rules, neither beat holding the market. From 1927 to September 2026 the market returned 10.31% a year, the trend rule 9.78% and the best valuation rule 8.08%. The trend rule halved the worst fall. The valuation rule has been out of the market since April 2013.
- Both factor premiums shrank after they were published. Value earned 5.27% a year before 1993 and 2.12% after; momentum 8.65% and 4.99%. Neither post-publication figure is statistically distinguishable from zero.
None of this is a forecast or a recommendation. The rules are the simplest versions of each idea, used to measure what each family of analysis can and cannot tell you.
Technical vs fundamental analysis: the difference in one table
| Fundamental analysis | Technical analysis | |
|---|---|---|
| Core question | What is this asset worth? | What is the price doing, and what does that say about the people trading it? |
| Input data | Earnings, cash flows, margins, debt, interest rates | Price, volume, volatility and transformations of them |
| Core assumption | Price returns towards value, eventually | Price patterns partly persist |
| Natural horizon | Years | Days to months |
| Typical output | A valuation and a decision to own or not own | An entry, an exit and a stop level |
| What our test found it knows | A quarter of the next decade’s return (CAPE, R² 25.6%) | Little about the average return; a lot about the next month’s risk |
| How it fails | Right about value, wrong about timing: out of the market for 13 years and counting | Whipsaws, and edges that fade once published |
Two signals, defined before the test
- Fundamental: CAPE. The S&P composite’s price divided by its average inflation-adjusted earnings over the previous ten years, published by Robert Shiller with data from 1871. It is the most widely cited valuation measure for the US market, and Campbell and Shiller (1998) showed its link with the following decade’s return.
- Technical: the 10-month moving average. Whether the market closed the month above or below the average of its last ten month-end levels. It is the trend rule we tested over 92 years in the 10-month moving average on the S&P 500, and roughly the monthly version of the 200-day average.
Both are the textbook form of their tradition, and neither was tuned. A professional analyst would add many things to either, which is exactly why we did not: every added condition is another chance to fit the past. Our article on how to read a backtest explains why.
Result one: they know different things
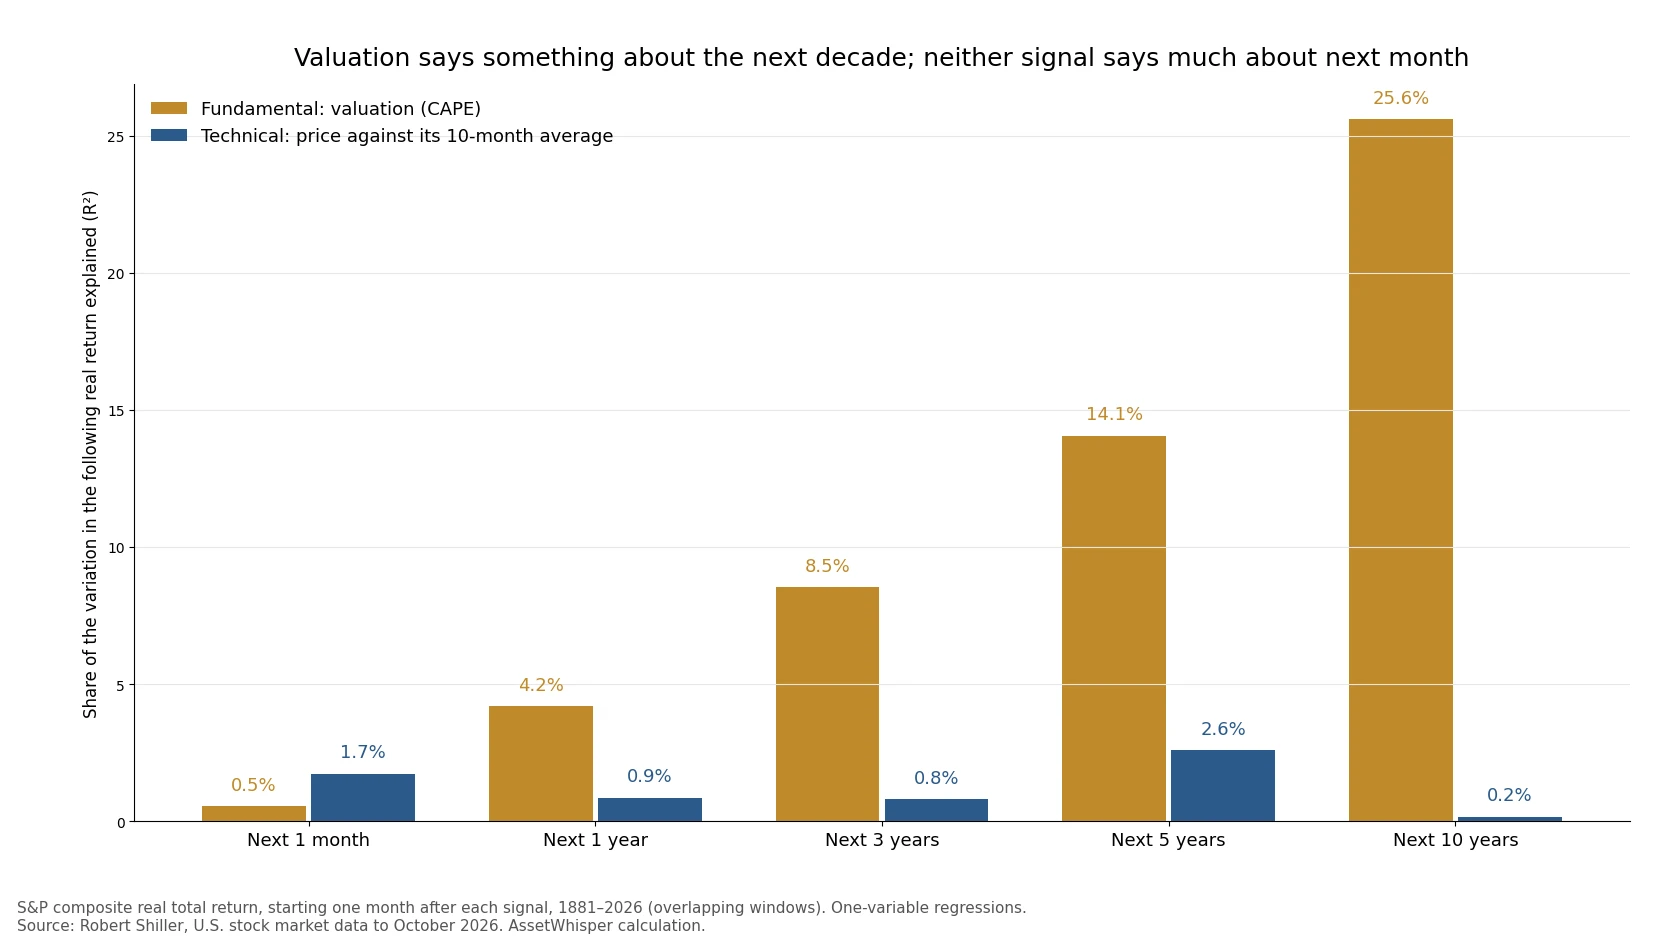
The first test asks how much of the following real return each signal explained, at five horizons, using every month since 1881. The measure is R², the share of the variation explained by a one-variable regression: 0% means the signal told you nothing, 100% that it told you everything.
| Share of the following real return explained (R²) | Next month | Next year | Next 3 years | Next 5 years | Next 10 years |
|---|---|---|---|---|---|
| Valuation (CAPE), 1881–2026 | 0.5% | 4.2% | 8.5% | 14.1% | 25.6% |
| Price vs 10-month average, 1881–2026 | 1.7% | 0.9% | 0.8% | 2.6% | 0.2% |
| Valuation (CAPE), 1950–2026 | 0.5% | 2.8% | 5.8% | 12.0% | 28.4% |
| Price vs 10-month average, 1950–2026 | 0.2% | 0.1% | 0.3% | 0.0% | 0.1% |
Valuation’s information grows with the horizon. CAPE knew almost nothing about next month and something real about the next decade: the higher the starting valuation, the lower the following ten years’ return, with a correlation of −0.51. That is the whole of the fundamental claim, and it holds in both halves of the sample.
The price trend explained almost nothing about the average return, at any horizon. Before 1950 its small next-month R² even had the “wrong” sign: a market further above its average did slightly worse the month after. Since 1950 it has been indistinguishable from zero. If the technical claim were “a rising market rises faster”, this table would end the argument.
It is not where the technical signal’s information is. Split the months by the trend state instead of fitting a line, and the difference is in the risk:
| US stock market, month-end, 1927 – Sep 2026 | Share of months | Next month’s average return | Next month’s volatility (a year) | Months worse than −10% that followed |
|---|---|---|---|---|
| Market closed above its 10-month average | 73% | +1.06% | 14.6% | 12 |
| Market closed below it | 27% | +0.70% | 26.0% | 19 |
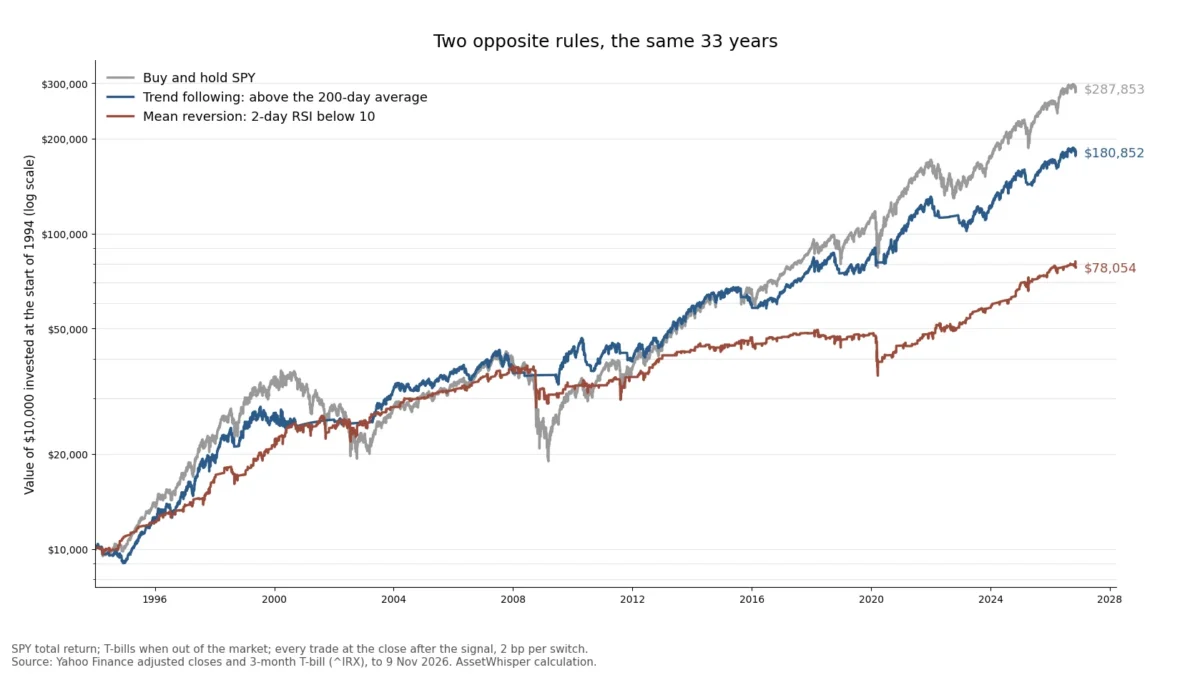
Below the average, the next month still went up on average, but the spread of outcomes was almost twice as wide, and 19 of the 31 worst months began from the 27% of months spent there. A trend signal is a crude volatility forecast. That is consistent with what we found for the 200-day rule in mean reversion vs trend following: fewer of the worst months, not a higher average.
Result two: what a high valuation has meant for the next decade
| CAPE at the start (months 1881–2016) | Months | Average real return, next 10 years | Worst | Best | Share of decades below 3% a year |
|---|---|---|---|---|---|
| Below 10 | 229 | 11.3% | 1.8% | 20.0% | 1% |
| 10 – 15 | 461 | 7.6% | −4.2% | 17.8% | 22% |
| 15 – 20 | 514 | 6.0% | −4.6% | 16.1% | 22% |
| 20 – 25 | 260 | 4.6% | −4.0% | 14.3% | 34% |
| 25 – 30 | 108 | 5.9% | −1.8% | 12.0% | 15% |
| Above 30 | 57 | −1.0% | −5.9% | 4.0% | 90% |
The gradient is there: cheap starts were followed by good decades and the most expensive by poor ones. Two features of the table matter as much as the gradient.
The ranges overlap almost completely. A CAPE between 15 and 20 was followed by anything from −4.6% to +16.1% a year. In August 2016 the CAPE was 26.9; a regression fitted on every earlier decade put the expected real return for the next ten years at 3.1% a year. The market delivered 11.6%. The typical error of that regression is 4.4 percentage points a year, about as large as the effect it measures over most of the range.
The extreme row is two episodes. All 57 months above 30 come from 1929 and from 1997–2002. That is two bubbles, not 57 independent observations, and the row cannot say what happens when valuations stay high for longer. The CAPE was 40.7 in October 2026, higher than in 98.9% of months since 1881 and below only the December 1999 peak of 44.2. The table describes what followed the previous two times; it does not date anything. Our article on the equity risk premium and real yields sets today’s valuation against bond yields.
Result three: the naive rule test
A signal that explains something is not yet a rule that pays. The standard test, the one we use in how to test a technical indicator, is to turn each signal into the simplest in-or-out rule and compare it with holding the market and with a fixed mix that has the same average exposure but no timing.
- Technical rule: hold the US stock market for the next month if it closed this month above its 10-month average; otherwise hold one-month Treasury bills.
- Fundamental rules: hold the market if the CAPE is below the median of every CAPE reading seen so far (or, in a milder version, below the 80th percentile so far); otherwise hold bills. The CAPE is used with a three-month lag, because earnings are published after the quarter ends.
| Jan 1927 – Sep 2026, no costs | Return a year | Sharpe ratio | Worst fall | Share of months in the market | Same exposure, no timing |
|---|---|---|---|---|---|
| Buy and hold | 10.31% | 0.45 | −83.7% | 100% | — |
| Technical: above the 10-month average | 9.78% | 0.55 | −42.9% | 72.8% | 8.73%, Sharpe 0.45, worst fall −71.5% |
| Fundamental: CAPE below its median so far | 8.08% | 0.41 | −59.8% | 35.9% | 6.17%, Sharpe 0.45, worst fall −42.8% |
| Fundamental: CAPE below its 80th percentile so far | 7.99% | 0.37 | −71.4% | 53.5% | 7.44%, Sharpe 0.45, worst fall −58.6% |
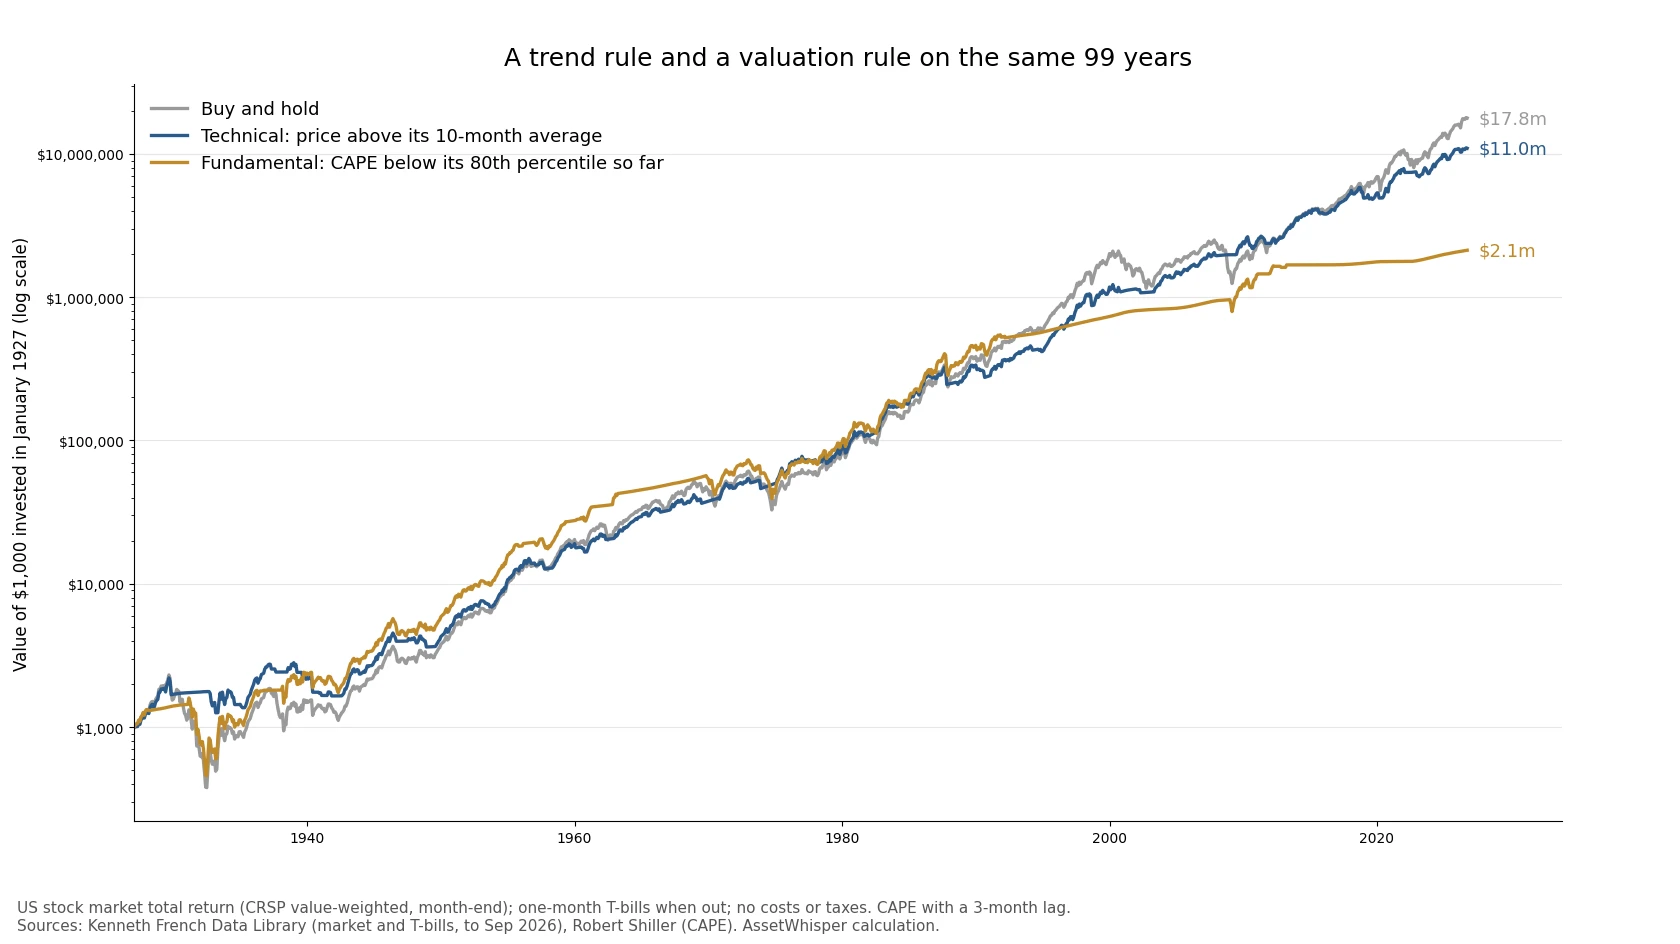
The trend rule did what its R² said it would. It earned 0.5 points a year less than the market, about a point more than a timing-free mix with the same exposure, and its worst fall was 42.9% instead of 83.7%. In 2000–02 it lost 0.8% while the market lost 40.9%; in 2007–09, 1.5% against 49.3%. It was hit in the fast falls: in the 1929–32 crash it still lost 19.8%. Its cost was the familiar one, slower returns in long bull markets: since 2010 it earned 9.38% a year against 14.15%. At 0.25% a switch, which is generous, its return fell to 9.37%.
The valuation rules were right about value and wrong about the decades. Until 1975 the median rule beat the market (9.23% a year against 8.29%). Then the CAPE rose above its long-run median and, with one short exception, stayed there. The rule has held the market in 1.4% of months since 1990 and none since August 2009. The milder 80th-percentile rule was out from April 1992 to December 2008 and has been out again since April 2013, 162 months and counting. It avoided the 2000–02 fall entirely (+7.9%) and earned 3.29% a year since 2010 while the market earned 14.15%.
The valuation rules beat their own same-exposure mix on return but not on risk-adjusted return, because when they were in the market they were fully in. And the two rules were nearly independent of each other: the correlation between their positions was −0.07. They answer different questions, as the first table said.
A warning about our own first attempt. Shiller’s price series is a monthly average of daily closes. Run on those averages, the technical rule returned 11.80% a year against 10.46% for holding, an apparent edge of 1.3 points. On month-end prices that edge becomes a 0.5-point shortfall. Averaging smooths a random series into one that seems to trend, a statistical artefact described by Holbrook Working in 1960. Any moving-average backtest built on monthly-average data has this bias, which is the kind of error how to read a backtest is about.
Result four: the factor record, before and after publication
Market timing is one use of each tradition. The other is choosing which stocks to own, and here each tradition has a famous academic factor. Value (HML: cheap stocks by book-to-market minus expensive ones) is fundamental analysis made systematic. Momentum (stocks that rose most over the past year minus those that fell most) is technical analysis made systematic. Ken French publishes both, monthly, from 1927.
| US long-short factor, average a year | 1927–1992 (before publication) | 1993 – Sep 2026 (after) | 2007 – Sep 2026 | Worst fall |
|---|---|---|---|---|
| Value (HML), fundamental | 5.27% (t 3.35) | 2.12% (t 1.08) | −1.38% | −57.8%, Dec 2006 – Sep 2020, not recovered |
| Momentum, technical | 8.65% (t 4.36) | 4.99% (t 1.75) | 1.67% | −78.4%, Jun 1932 – Sep 1939 |
| Half in each | 6.96% (t 7.76) | 3.55% (t 2.27) | 0.15% | −40.7%, Nov 2008 – Dec 2020, not recovered |
Value had been noticed before, but Fama and French’s 1992 paper made it the standard factor; Jegadeesh and Titman published momentum in 1993. Since then both premiums have fallen by roughly half, and a t-statistic of 1.08 or 1.75 is not enough to rule out zero. McLean and Pontiff (2016) found the same pattern across 97 published return predictors: returns 26% lower out of sample and 58% lower after publication. The fundamental factor has suffered more than the technical one in this sample: value’s worst fall lasted fourteen years and the factor is still 33% below its 2006 peak. Momentum carries the other kind of risk: it lost 52.6% in one month, August 1932, and its crashes come in sharp rebounds after bear markets, as Daniel and Moskowitz (2016) document. Our momentum article has the full record.
The last row is the closest thing to an argument for combining them. Value and momentum have been negatively correlated (−0.41 monthly), as Asness, Moskowitz and Pedersen (2013) found in eight asset classes, so half in each had a much higher t-statistic than either. It also earned almost nothing from 2007 to 2026.
What the published evidence says
On technical analysis. Park and Irwin (2007) reviewed 95 modern studies: 56 found profits for technical rules, 20 found losses and 19 were mixed. The positive results cluster in older data. Brock, Lakonishok and LeBaron (1992) found moving-average and breakout rules informative on the Dow from 1897 to 1986; Sullivan, Timmermann and White (1999) confirmed that the best of thousands of rules survived a correction for data snooping in that period, and then showed that it did not work from 1987 to 1996. Lo, Mamaysky and Wang (2000) found that some chart patterns carry statistically detectable information about the distribution of the next returns, more about their shape than their mean. That matches our first table.
On fundamental analysis. Campbell and Shiller (1998) showed that valuation ratios forecast long-horizon market returns. Goyal and Welch (2008) tested the main valuation and macro predictors out of sample and found that most would not have helped an investor using them in real time. Our rule test is a small version of that finding: the information is real, but a rule that acts on it can spend decades on the wrong side.
The common thread is decay. Both families show edges that were larger before they were documented and before computers made them cheap to test. Andrew Lo’s adaptive markets hypothesis describes this: predictability is not a fixed property of a market but rises and falls as participants learn.
The disadvantages, stated plainly
Disadvantages of fundamental analysis
- It says nothing useful about timing. CAPE explained 0.5% of the next month’s return and 4.2% of the next year’s. A valuation rule was out of the market for 162 months, and counting.
- Its estimates are imprecise. Even at the ten-year horizon, where valuation works best, the typical error was 4.4 points a year. In a discounted cash flow model, small changes in the growth or discount rate move the answer by more than the margin of safety.
- It is slow and the data are public. Everyone reads the same filings at the same moment; an edge needs a different interpretation or a longer horizon than other holders, not better arithmetic.
- Its best-known premium has faded. Value earned 2.12% a year after 1993 and lost money from 2007 to 2026.
Disadvantages of technical analysis
- It predicts little about the average return. The trend signal explained under 3% of the following return at every horizon, and nothing since 1950.
- It is easy to fool yourself. Chart reading is subjective, and rule testing invites data snooping; a single averaging choice added 1.3 points a year to our own first backtest.
- It ignores solvency. A chart cannot see a covenant breach or a fraud; price-based methods handle continuous markets better than sudden events.
- It costs turnover and lagging. The trend rule switched 1.5 times a year and trailed the market by 4.8 points a year since 2010.
Which one your decision actually needs
| If your decision is… | The evidence points to |
|---|---|
| What return to plan on over the next ten years | Valuation. It is the only one of the two that knew anything at that horizon, with a wide error. |
| Whether to be in or out of the market next month | Neither predicts the return. The trend state tells you something about how volatile the month is likely to be. |
| How to limit the worst fall | A trend rule halved it in this test, at a cost in return. So does simply holding less in stocks; compare it with the same-exposure mix. |
| Which stocks to own | Both have factor evidence, smaller since publication. Most investors capture it more cheaply through index funds than through their own selection. |
| How much to put in one idea | Neither. That is position sizing, and it usually matters more than which analysis produced the idea. |
Professional practice often combines the two: fundamental analysis to decide what is worth owning, technical tools to decide when to act and where risk is defined. Our data support the division of labour in one specific sense: the two signals were nearly uncorrelated and informative at different horizons. They do not show that the combination beats holding the market.
Where quantitative analysis fits
The technical-versus-fundamental framing comes from a time when analysis was done by hand. Quantitative analysis is not a third camp but a method: it turns an idea from either tradition into a rule, tests it on data the idea was not built from, and measures the result against an honest benchmark. Momentum and mean reversion are technical ideas made testable; value and profitability are fundamental ones. What separates quantitative work is the requirement to state in advance what would prove the idea wrong. See which algorithmic trading strategies are actually profitable for the main families after costs.
What the evidence supports, and what it does not
It supports:
- Valuation carries information about long-horizon returns: a quarter of the variation in the next decade, little about the next year.
- Price trend carries information about risk: the months after the market fell below its 10-month average were almost twice as volatile.
- Both factor premiums existed over a century of US data, and both shrank after publication.
It does not support:
- That either method, in its simplest systematic form, beats holding the market. Neither rule did from 1927 to 2026.
- That a high CAPE dates a fall. The valuation rule has been out since April 2013, and the expensive row of the table rests on two episodes.
- That one method is “better”. They answer different questions at different horizons, and their failures are different: fundamental analysis is usually wrong about timing, technical analysis about persistence.
- Any conclusion after taxes. Both rules realise gains that a buy-and-hold investor defers.
Frequently asked questions
What is the difference between technical and fundamental analysis?
Fundamental analysis estimates what an asset is worth from the business behind it: earnings, cash flows, debt, interest rates. Technical analysis studies price and volume to judge what other investors are doing. On 145 years of US data, a valuation signal (CAPE) explained 25.6% of the following decade’s real return; a price-trend signal explained less than 3% of the return at any horizon but flagged the more volatile months.
Which is better, technical or fundamental analysis?
Neither, in general; they are informative at different horizons. Valuation knew something about the next ten years and almost nothing about the next month. The price trend knew little about average returns but something about risk. Turned into simple rules from 1927 to 2026, neither beat holding the market: 10.31% a year for the market, 9.78% for the trend rule and 8.08% for the best valuation rule.
Does technical analysis actually work?
The evidence is mixed and depends on the period. Park and Irwin (2007) found that 56 of 95 modern studies reported profits for technical rules, mostly in older data. In our test a 10-month moving-average rule earned 0.5 points a year less than the market from 1927 to 2026 but cut the worst fall from 83.7% to 42.9%. Momentum, the systematic version of trend, earned 8.65% a year before its 1993 publication and 4.99% after.
Does fundamental analysis work?
For long-horizon expectations, partly. Starting valuations above a CAPE of 30 were followed by an average real return of −1.0% a year over the next decade, against 11.3% below a CAPE of 10. But the error is large (4.4 points a year), a valuation rule has been out of the market since 2013, and the value factor earned 2.12% a year after 1993 against 5.27% before.
Which of the following is a disadvantage of fundamental analysis?
The most commonly cited disadvantages are that it gives no guidance on timing, that its valuations are highly sensitive to assumptions, and that it is time-consuming while the underlying data are public to everyone at once. In our data, valuation explained 0.5% of the next month’s market return and 4.2% of the next year’s.
What is the difference between quantitative and technical analysis?
Technical analysis is a source of ideas about price behaviour. Quantitative analysis is a method for testing ideas, technical or fundamental, as explicit rules on data, against benchmarks, out of sample. Momentum is a technical idea made quantitative; the value factor is a fundamental one.
Can you use technical and fundamental analysis together?
Yes, and the data give one reason: the two signals were nearly independent (the correlation between the two rules’ positions was −0.07), and the value and momentum factors were negatively correlated (−0.41). Half in each factor had a steadier record than either. It still earned almost nothing from 2007 to 2026, so combining is not a guarantee.
How we calculated this
- Data: Robert Shiller’s monthly US stock market data (S&P composite price, dividends, CPI and CAPE), January 1871 to October 2026; the Kenneth French Data Library’s US market return (CRSP value-weighted, all NYSE, AMEX and Nasdaq stocks), one-month T-bill rate, HML and momentum factors, to September 2026.
- Horizon test: one-variable regressions of the following real total return (annualised) on the log of CAPE and on the price’s distance from its 10-month average, for each month from 1881. The return window starts one month after the signal, because Shiller’s prices are monthly averages and an adjacent window would overlap the signal. Windows overlap one another, so the R² describes the data; it is not a significance test.
- Volatility by trend state: CRSP market, month-end levels, trend state at the end of each month and the return of the following month.
- Rules: monthly, January 1927 to September 2026, decided at the end of a month and applied to the following month. The trend rule uses CRSP month-end total-return levels. The valuation rules compare the CAPE, lagged three months, with the median or 80th percentile of all CAPE readings available at the time (at least ten years of them). Out of the market means one-month T-bills. Costs, where stated, are charged per switch. Nothing is after tax.
- Same-exposure mix: a monthly-rebalanced mix of the market and T-bills with the rule’s average share of months in the market.
- Factors: arithmetic average monthly return × 12; t-statistics from the monthly series; worst fall and recovery from the compounded long-short series.
- The calculation script and its output, kept with the article, reproduce every figure.
Sources
- Campbell, J. Y. and Shiller, R. J., “Valuation Ratios and the Long-Run Stock Market Outlook”, Journal of Portfolio Management, 24(2), 1998.
- Goyal, A. and Welch, I., “A Comprehensive Look at the Empirical Performance of Equity Premium Prediction”, Review of Financial Studies, 21(4), 2008.
- Park, C.-H. and Irwin, S. H., “What Do We Know About the Profitability of Technical Analysis?”, Journal of Economic Surveys, 21(4), 2007.
- Brock, W., Lakonishok, J. and LeBaron, B., “Simple Technical Trading Rules and the Stochastic Properties of Stock Returns”, Journal of Finance, 47(5), 1992.
- Sullivan, R., Timmermann, A. and White, H., “Data-Snooping, Technical Trading Rule Performance, and the Bootstrap”, Journal of Finance, 54(5), 1999.
- Lo, A. W., Mamaysky, H. and Wang, J., “Foundations of Technical Analysis: Computational Algorithms, Statistical Inference, and Empirical Implementation”, Journal of Finance, 55(4), 2000.
- Fama, E. F. and French, K. R., “The Cross-Section of Expected Stock Returns”, Journal of Finance, 47(2), 1992.
- Jegadeesh, N. and Titman, S., “Returns to Buying Winners and Selling Losers: Implications for Stock Market Efficiency”, Journal of Finance, 48(1), 1993.
- McLean, R. D. and Pontiff, J., “Does Academic Research Destroy Stock Return Predictability?”, Journal of Finance, 71(1), 2016.
- Asness, C. S., Moskowitz, T. J. and Pedersen, L. H., “Value and Momentum Everywhere”, Journal of Finance, 68(3), 2013.
- Daniel, K. and Moskowitz, T. J., “Momentum Crashes”, Journal of Financial Economics, 122(2), 2016.
- Working, H., “Note on the Correlation of First Differences of Averages in a Random Chain”, Econometrica, 28(4), 1960.
- Lo, A. W., Adaptive Markets: Financial Evolution at the Speed of Thought, Princeton University Press, 2017.
- Data: Robert Shiller, U.S. stock market data and CAPE; Kenneth French, Data Library; both retrieved 11 November 2026.
Related reading
- How to test a technical indicator before trusting it — the same-exposure and random-timing benchmarks used here.
- The 10-month moving average on the S&P 500 — the trend rule, bear market by bear market.
- Does momentum investing work? — the technical factor, and its crashes.
- How to identify undervalued assets — fundamental analysis applied to a single decision.
- How to read a backtest without fooling yourself — the errors, including averaging, that inflate results.
This article is general information, not personalised investment advice. It does not take into account the financial situation, objectives or risk tolerance of any individual reader, and the same text is distributed to all readers. The rules tested are illustrations of two kinds of analysis, not trading recommendations, and the valuation figures describe history, not a forecast. Past performance, real or simulated, does not indicate future results, and capital is at risk.